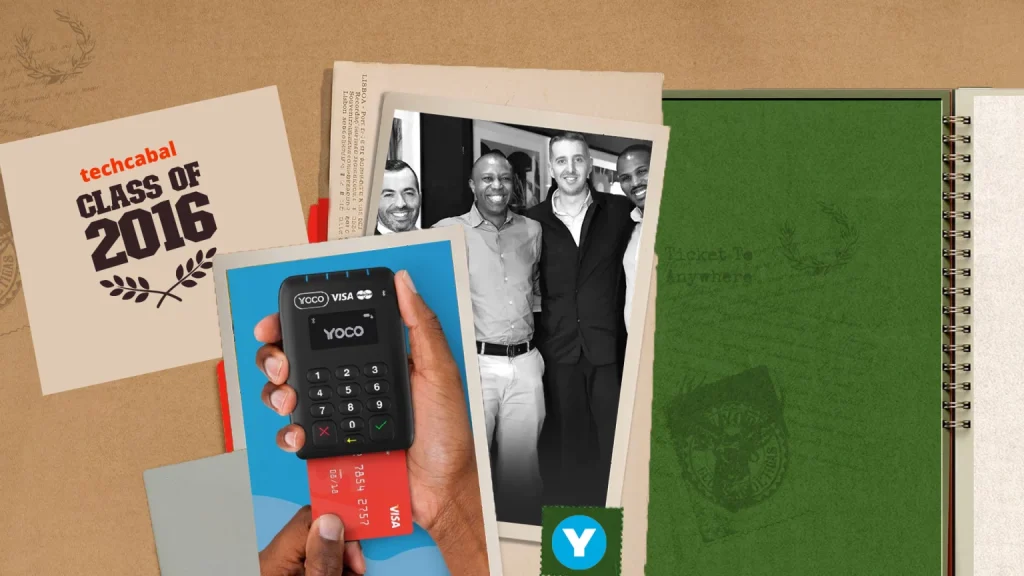
Yoco began with a relatively simple proposition: give small businesses access to card-payment technology without the complexity traditionally associated with accepting electronic payments. What started with card machines has since developed into a broader fintech platform serving entrepreneurs across South Africa.
The company’s early focus was shaped by a practical problem. Many small and informal businesses struggled to accept card payments because traditional payment systems were often expensive, difficult to access or designed around the needs of larger companies. Yoco saw an opportunity to make card acceptance easier for smaller merchants.
But putting payment terminals into the hands of businesses was only the beginning.
For small merchants, accepting a payment is connected to a much larger set of challenges: understanding cash flow, managing sales, accessing financial services and finding affordable tools to run a business. As Yoco grew, those needs pushed the company beyond the card machine itself.
Its evolution reflects an important lesson in African fintech. Successful financial technology companies often do not expand because their original product suddenly becomes irrelevant. They expand because the original product gives them a close relationship with customers and reveals additional problems that need solving.
Yoco’s card machines provided precisely that relationship. Every transaction generated insight into how merchants operated, while the payment infrastructure created a recurring connection between the company and its customers. That positioned Yoco to build additional financial and business tools around the merchant.
The approach also reflects the realities of operating in emerging markets. Entrepreneurs need technology that works within the constraints of their businesses rather than products designed for ideal conditions. Affordability, ease of use and reliability can matter just as much as sophisticated features.
Over time, Yoco expanded its offering to support more aspects of running a business, including payments, business management and access to financial services. The broader strategy effectively transformed the company from a card-terminal provider into a technology platform for small businesses.
This evolution is significant because small and medium-sized businesses represent a major part of Africa’s economy but often remain underserved by traditional financial institutions. Many have limited financial histories, inconsistent documentation or revenue patterns that make conventional banking products difficult to access.
Fintech companies can use transactional relationships to build alternative ways of understanding these businesses. Payment data, for example, can provide a clearer picture of a merchant’s activity and potentially support services that were previously unavailable to them.
Yoco’s journey therefore illustrates a broader principle: survival can be an engine of innovation. A company that begins by solving one narrow problem may discover that staying relevant requires solving several connected problems.
The card machine was the entry point. The merchant became the customer relationship, and the wider business ecosystem became the opportunity.
For African fintech founders, that may be the more important lesson. Building a durable company is not always about predicting the perfect product from day one. Sometimes it is about solving one painful problem exceptionally well, staying close to customers and allowing their changing needs to determine what comes next.
Leave a Reply